Recently, the US Federal Reserve increased interest rates by 0.25% (CNBC). It may not seem like much, but it heralds further increases in interest rates, and it basically represents the failure of Trump policy. Let’s talk about it.
What are interest rates?
FYI, this is all stuff that you can learn about from more politically impartial sources, such as Wikipedia, or websites promoting financial literacy. I’m not saying anything new.
“Interest rates” is a generic term that describes how expensive it is to maintain debt, e.g. if you have a mortgage or credit card debt, you have to pay interest on that debt. But in this context, I’m referring to the Effective Federal Funds Rate (EFFR), which is a matter of US economic policy. The EFFR represents the interest rates that US banks pay on their debts to the US Federal Reserve. The EFFR is not identical to the interest rates that you pay on your own debts, but they’re strongly connected via market mechanisms.
Okay, but why are banks borrowing money?
When you deposit money in a bank, they don’t hold all that money in a vault, they turn around and invest the money. But you still need to be able to withdraw money when you need it, so banks maintain a certain amount of money on hand (aka liquidity). In fact, banks are strictly required to maintain a minimum amount of liquidity. If banks ever have too little liquidity, they borrow money from other banks that have too much. Or, they borrow money from the US Federal Reserve Bank.
So by setting the EFFR, the US Federal Reserve is basically setting the price of liquidity. And that affects the entire financial system.
If interest rates are low, then liquidity is cheap. You can borrow money to buy a house at relatively low interest rates. You can borrow money to start a new business. You can even invest in businesses that produce relatively little value to society, such as cryptocurrency or Twitter.
If interest rates are high, then liquidity is expensive. Starting a business is harder. Investors demand companies produce immediate profit, even if that means enshittifying their product. Even the US national debt becomes more of a concern, because the government, too, pays a higher interest rate.
Depending on your financial position, you may stand to personally gain or lose from higher interest rates. For example, if you have a fixed interest mortgage, lucky you, you’re protected. But the purpose of adjusting interest rates is obviously not to benefit some individuals and punish others, it’s for the health of the entire economy. In case of a recession or financial panic (e.g. the 2008 financial crisis), the Feds will lower interest rates to inject more money into the system. In case of supply shocks or inflationary spiral (e.g. recent years), the Feds will raise interest rates, basically discouraging spending and tamping down inflation.
The current hikes
So, here’s the EFFR over the last 10 years.
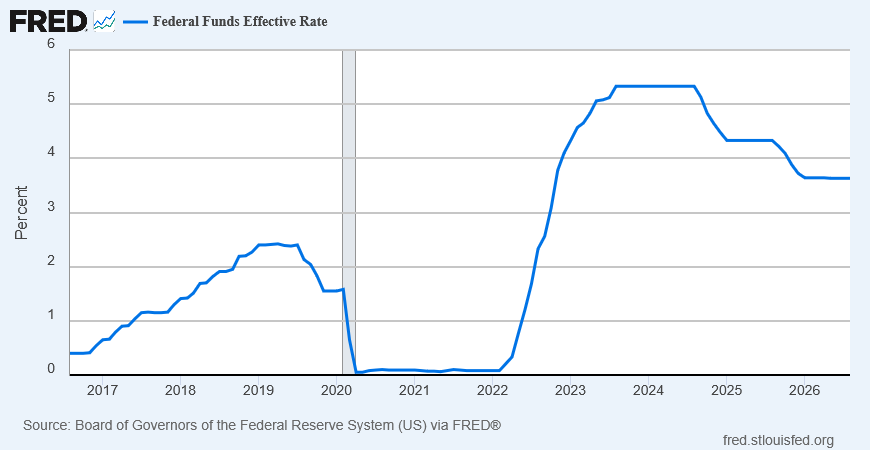
Source: FRED. The graph doesn’t reflect the latest increase in EFFR this month.
In 2020, the Feds suddenly cut rates in response to the pandemic, basically financial relief in the face of hard times. But it couldn’t last. In 2022, inflation started going up, attributed to pandemic stimulus checks, supply chain disruptions, and the Russian invasion of Ukraine. So the Feds responded by increasing interest rates. Under Biden, the economy was recovering and interest rates were slowly turning around. But Biden also took the blame, and this is probably the biggest reason why Democrats lost the election in 2024.
Trump put the brakes on economic recovery, as I’ve already discussed. He promised tariffs and immigration enforcement. So the Feds, conservative though they are, were concerned he’d make good on those promises, and slowed down interest rate cuts over the next few years.
The latest interest rate hike is pretty strongly related to another Trump policy: war with Iran. It turns out that if you take 20% of the world’s oil supply, and lock it behind the Strait of Hormuz, things get more expensive. Inflation goes up, and the Feds increase interest rates to tamp it down.
Trump, for his part, has been demanding that the Feds cut interest rates. He demanded it in 2025, and is demanding it today. He even installed Kevin Warsh as chair of the Federal Open Markets Committee (which decides interest rates), in an effort to pressure interest rate cuts. But the latest vote was unanimous, with even Warsh voting to raise interest rates.
Why has Trump been demanding interest rate cuts? It’s nonsensical. The interest rate hikes are easily attributable to his own damn policies. He’s openly advocating a policy of runaway inflation.
I’ve wondered if maybe Trump stands to personally benefit from lower interest rates. For instance, if he personally holds variable-rate loans. I found a source saying that he did, as of 2019. So basically, he’s advocating a nonsensical policy because of personal corruption. Unforgivable.
But another source argues that he’s demanding interest rate cuts in order to deflect blame onto the Feds. Hard to tell who exactly this would fool, as it requires you to simultaneously understand federal interest rates, and not understand federal interest rates. In any case, also unforgivable.
This has been your periodic reminder that the Nazis do not make the trains run on time. They just blame immigrants when they themselves screw up the trains.